Mortgage Rates • Calculators • Refinancing

Mortgage Rates, Refinance & Loan Calculators for Smarter Borrowing

Compare mortgage rates, estimate monthly payments, explore refinancing options, and use loan calculators and financial guides to make informed borrowing decisions.

Featured Mortgages

Mortgage Payment Calculator

Home Price $400,000
Down Payment $80,000
Interest Rate 5.98%
Loan Term 360 Months
Estimated Monthly Payment $0
Advertisement

Home Buying & Mortgage Approval Guides

  • Get a Mortgage Without a Social Security Number

    Can You Get a Mortgage Without a Social Security Number?

  • Mortgage for Foreign Nationals

    Mortgage for Foreign Nationals: Requirements, Rates and Options

  • Immigration Status Can Affect Mortgage Eligibility

    How Immigration Status Can Affect Mortgage Eligibility

  • How Lenders Calculate Income for Self-Employed Borrowers

    How Lenders Calculate Income for Self-Employed Borrowers

  • Get a Mortgage When You’re Self-Employed

    How to Get a Mortgage When You’re Self-Employed

  • Get a Mortgage in the United States

    Can Non-US Citizens Get a Mortgage in the United States?
Current Mortgage Rates & Market Trends

Mortgage rates fluctuate based on market conditions, lender policies, and loan types. Fixed and adjustable options offer different advantages for homebuyers. This card provides a visual snapshot of current trends to help gauge general rate ranges. We update this information regularly to reflect changes and ensure you see the most relevant mortgage insights.

Advertisement

Mortgage Rates by Year

Source: Freddie Mac Primary Mortgage Market Survey®

Mortgage Rate Drop Savings Calculator

Mortgage Rate Drop Savings

Enter your loan details and instantly see how much you could save if mortgage rates drop.

Current Monthly Payment $0
New Monthly Payment $0
Estimated Monthly Savings $0
New Interest Rate 0%

Next Step: Find Your Best Mortgage Option

Now that you know your savings potential, take our quick mortgage quiz to see which loan type fits you best (FHA, VA, USDA, Conventional, Jumbo, or Refinance).

🔥 Take the Mortgage Quiz & Get My Best Loan Match
Advertisement

Mortgage Affordability, Credit & Debt

  • Buying a House With Credit Card Debt

    Buying a House With Credit Card Debt

  • Buying a House While Paying Off Debt

    Buying a House While Paying Off Debt

  • Buying a House While Living With Parents
    Buying a House While Living With Parents
Refinance & Mortgage Savings

Specialized Mortgage Options

Alternative & Investment Property Mortgages

  • Construction-to-Permanent Loan

    Construction-to-Permanent Loan Explained

  • FHA 203(k) Loan

    FHA 203(k) Loan Explained

  • Reverse Mortgage Pros and Cons

    Reverse Mortgage Pros and Cons

Mortgage Rates, Updates & Tax Information

  • Buyers Are Taking Smaller Mortgage Risks Recently

    Buyers Are Taking Smaller Mortgage Risks Recently

  • Mortgage Borrowing Behavior Is Gradually Changing

    Mortgage Borrowing Behavior Is Gradually Changing

  • Buyers Are Thinking Long-Term Before Accepting Mortgages
    Buyers Are Thinking Long-Term Before Accepting Mortgages
Frequently Asked Questions

Your monthly mortgage payment depends on several factors, including the home price, down payment, interest rate, and loan term. A larger down payment generally reduces the amount you need to borrow, while a higher interest rate can increase both your monthly payment and total interest cost.

Your actual housing cost may also include property taxes, homeowners insurance, and mortgage insurance, depending on your situation. That means looking only at the loan principal and interest may give you an incomplete picture of what owning the home will cost each month.

Before shopping for a home, try several combinations of home prices, down payments, rates, and loan terms to find a payment that fits your budget.

Use our mortgage calculator to estimate your monthly payment and compare different home-buying scenarios.

How much house you can afford depends on more than your annual income. Lenders may consider your monthly income, existing debts, credit profile, down payment, interest rate, loan type, taxes, insurance, and other financial obligations when evaluating your borrowing capacity.

However, the amount a lender may approve isn’t necessarily the amount you should spend. Your personal budget also needs to leave room for groceries, utilities, maintenance, emergencies, savings, and other lifestyle expenses.

A good starting point is to estimate a comfortable monthly housing payment and then work backward to determine a reasonable home price. You can also compare your income and debts to understand how lenders may evaluate your application.

Our mortgage pre-approval calculator can help estimate a potential approval range based on income, debts, down payment, rate, loan term, and credit profile.

Buying a home usually requires more cash than just the down payment. Depending on the loan and transaction, you may also need money for closing costs, lender fees, appraisal, title services, prepaid taxes and insurance, moving expenses, and other upfront costs.

Your required down payment can vary depending on the mortgage program and your financial situation. A larger down payment may reduce your loan amount and potentially lower certain costs, but using all of your savings for the purchase can leave you without an emergency cushion.

Before setting a home-buying budget, estimate both your cash needed upfront and your ongoing monthly costs. This gives you a more realistic picture of what you can afford.

For example, buyers using VA financing can estimate their upfront costs with our VA closing cost calculator.

Your home equity is the portion of your home’s value that isn’t covered by your remaining mortgage balance. In simple terms, if your home is worth $400,000 and you owe $300,000 on the mortgage, you have approximately $100,000 in equity.

Equity can grow in two main ways: by paying down your mortgage principal and by an increase in the home’s market value. However, market values can also fall, so your equity isn’t guaranteed to increase every year.

Knowing your equity can be useful when considering selling, refinancing, removing mortgage insurance, or exploring home-equity borrowing. It can also give you a clearer picture of your overall household net worth.

Learn more about what home equity means and how mortgage payments contribute to the portion of your home you own.

Yes, every mortgage loan includes an interest rate, which is the cost charged by the lender for borrowing money. The interest rate can be fixed or variable depending on the loan agreement. Fixed rates remain the same throughout the loan term, while adjustable rates can change over time. You can compare different options by checking current mortgage rates before applying.

Property taxes can add a significant amount to the monthly cost of owning a home. The amount depends on the property’s assessed value, local tax rate, municipality, and other location-specific factors.

This is important because a mortgage payment that looks affordable based only on principal and interest may become considerably higher after property taxes and homeowners insurance are included. Some homeowners pay property taxes through an escrow account as part of their monthly mortgage payment, while others handle them separately.

When estimating affordability, don’t stop at the mortgage payment shown by a basic calculator. Include taxes and other recurring housing costs to get a more realistic monthly budget.

If you’re buying in Canada, our property tax calculator can estimate annual and monthly property taxes based on property value and province. Actual taxes can vary by municipality.

A 15-year and 30-year mortgage can produce very different monthly payments and total interest costs. A 15-year mortgage typically requires larger monthly payments, but the loan is repaid faster and can result in substantially less interest over the life of the loan.

A 30-year mortgage generally provides a lower monthly payment, which can make homeownership easier to fit into your budget. However, you’ll typically pay interest for a much longer period.

The better option depends on your income, financial goals, savings, and how much payment flexibility you want. A shorter term isn’t necessarily better if the higher payment leaves you without enough room for emergencies or other priorities.

Before choosing, compare both scenarios using the same home price, down payment, and interest rate. Our mortgage term calculators can help you compare different repayment periods.

Even a relatively small change in your mortgage interest rate can affect your monthly payment and total interest because mortgages are usually repaid over many years. The effect becomes more noticeable as the loan amount or repayment period increases.

For example, two borrowers could finance the same home with the same down payment but receive different interest rates. The borrower with the lower rate will generally have a lower principal-and-interest payment and may save substantially over the life of the mortgage.

However, don’t assume the lowest advertised rate is automatically the cheapest mortgage. Fees, discount points, loan type, and other terms can affect the overall cost.

The easiest way to understand the difference is to run both rates using the same loan amount and term. Our mortgage calculator lets you change the interest rate and compare how different scenarios affect your estimated payment.

Refinancing can make sense when a new mortgage meaningfully improves your financial situation, but a lower interest rate by itself isn’t enough to guarantee savings. You should compare your current loan with the proposed refinance, including the new rate, monthly payment, closing costs, remaining balance, and new repayment term.

For example, refinancing may reduce your payment but extend the debt for many additional years. That could lower your monthly expenses while increasing your total interest cost. On the other hand, refinancing to a shorter term could increase the payment while reducing long-term interest.

Your break-even point is also important. If refinancing costs $6,000 and saves you $300 per month, you’d need roughly 20 months just to recover that cost.

Before deciding, compare the numbers rather than reacting to a rate change alone. Our guide on when refinancing makes sense explains the factors worth reviewing.

Private mortgage insurance, or PMI, can add to your monthly housing cost when you have a conventional mortgage with a relatively small down payment. As you build equity, you may eventually become eligible to have PMI removed, depending on your loan terms and applicable requirements.

One important factor is your loan-to-value ratio (LTV). As your mortgage balance falls relative to the home’s value, your equity position improves. Home appreciation can also affect your LTV, although you should not assume an increase in value automatically results in PMI cancellation.

If you’re considering PMI removal, check your mortgage documents and contact your loan servicer to understand the specific requirements that apply to your loan. Refinancing may be another option in some situations, but it comes with its own costs.

Before making a decision, calculate your current loan balance, estimated home value, and equity position so you can understand where you stand.

Advertisement

Get Answers Before You Borrow

Buying a home, refinancing, or comparing a loan? Explore practical answers about mortgage rates, qualification, payments, refinancing, borrowing costs, and more. Find helpful explanations and calculators to better understand your options before making a financial decision.

Personal Finance & Smart Money Guides
travelling with friends

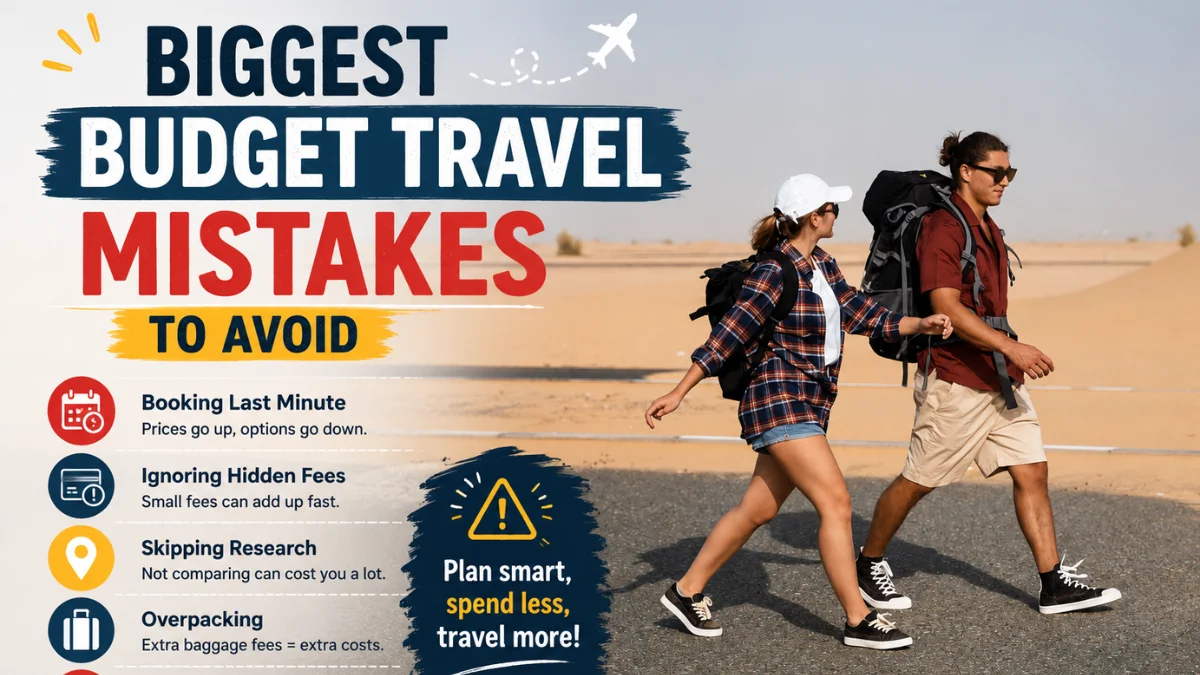
Want to travel more without putting unnecessary pressure on your wallet? Explore Budget Travel & Smart Spending for practical ideas to reduce trip costs, plan affordable getaways, find smarter ways to spend, and make your travel budget go further.

From transportation and accommodation to everyday vacation expenses, these guides can help you make more informed decisions while still enjoying the experiences that make traveling worthwhile.
 

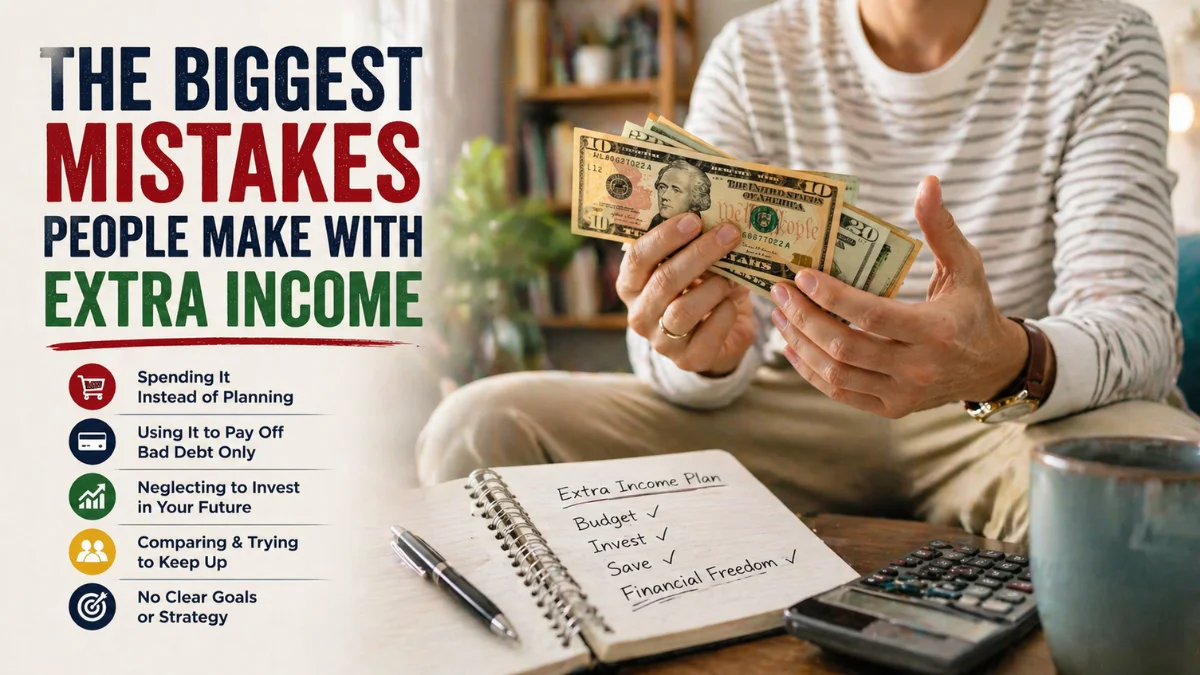
Small changes in the way you spend can make a meaningful difference over time. Our Saving Money & Smart Spending guides cover practical ways to reduce everyday expenses, manage your spending, find potential savings, and make better use of your income.

Whether you’re trying to cut unnecessary costs or simply become more intentional with your money, you’ll find ideas designed to help you spend smarter and save more.
Everyday expenses can have a major impact on your financial decisions. Explore Cost Of Living & Life Style for useful insights into housing, groceries, transportation, entertainment, travel, and other lifestyle expenses.

These guides can help you understand where your money goes, compare different costs, and make more informed choices about the lifestyle you want while keeping your overall spending and financial goals in mind.


Looking for ways to increase your income beyond your regular paycheck? Explore Side Income & Extra Money for practical ideas about side hustles, extra earnings, freelance opportunities, and other ways people can potentially supplement their income.

Whether you’re saving for a major goal, building an emergency fund, or simply looking for additional financial flexibility, these guides can help you explore different approaches and understand what may work for your situation.


What to Read Next?
Advertisement

Looking for the Right Loan Option?

From personal and auto loans to student, business, and online loans, explore your options and understand what to consider before borrowing.

Disclaimer: MortgageRatesChecker is not a lender and does not make credit decisions. We connect users with third-party lenders and service providers. We do not guarantee loan approval, rates, or terms. Loan offers are subject to eligibility and may vary by lender, state, and applicant profile. Short-term loans are not a long-term financial solution. This website does not charge users any fees for its services. We may earn compensation from partner lenders. Not all products are available in all states. Learn more in our Advertiser Disclosure.